Dow Jones Industrial Average: 52,002.41 (-0.34%, -175.28)
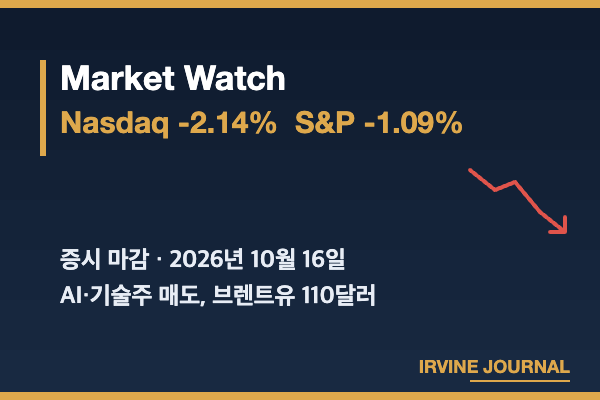
S&P 500: 7,659.44 (-1.09%, -84.62)
Nasdaq Composite: 26,140.03 (-2.14%, -572.99)
Russell 2000: 2,721.37 (-1.66%)
U.S. stocks fell Friday as renewed scrutiny of the AI trade hit software and chip stocks and a surge in oil prices added to inflation worries. An early broad rally unraveled by midday: the Nasdaq posted its worst day since June 5, and the S&P 500 erased its October gain. For the week, the Nasdaq fell about 4.5% — its worst week since late June — snapping a monthlong winning streak, while the Dow held up better as investors rotated out of tech.
Oil spike: Brent crude touched $110 a barrel for the first time since May as Iran escalated attacks in the Strait of Hormuz, and U.S. crude held above $100 — another inflation headache after this week's hot consumer and wholesale price reports. The Cboe Volatility Index (VIX) jumped more than four points, briefly reaching 22.31.
AI and software selling: Software stocks lost roughly $130 billion in combined value at one point, and debt worries returned to CoreWeave. Bank of America argued the AI trade remains "resilient," citing near-100% utilization of deployed AI infrastructure.
CoreWeave (CRWV) -11.9%, giving back Thursday's rebound amid concerns about its debt-heavy balance sheet.
Moderna (MRNA) about -9% as investors took profits after a 600%-plus rally this year.
Palantir (PLTR) about -7%, heading toward correction territory a week after a record close.
Meta (META) -3.7% and Netflix (NFLX) -2.9% ahead of quarterly results.
Tesla (TSLA) -2.1% to $354.72, erasing early gains after unveiling its thruster-equipped Roadster; Tesla reports earnings next week.
Visa and Mastercard hit records earlier in the session as money rotated out of tech.
Earnings from Tesla, Netflix and Meta headline next week. Traders now see roughly a 15% chance of an October rate hike after Fed Chair Kevin Warsh declined to preview the next decision; the Fed meets October 28, followed by the PCE inflation report on October 29.
10월 16일(금) 뉴욕 증시는 다우 52,002.41(-0.34%), S&P 500 7,659.44(-1.09%), 나스닥 26,140.03(-2.14%)으로 마감했습니다. AI 관련 우려가 다시 커지며 소프트웨어·반도체주가 하락했고, 이란의 호르무즈 해협 공격 확대로 브렌트유가 5월 이후 처음 배럴당 110달러를 찍으면서 인플레이션 우려가 더해졌습니다. 나스닥은 6월 5일 이후 최악의 하루를 기록했고, 이번 주 약 4.5% 하락해 6월 말 이후 최악의 한 주를 보냈습니다.
종목별로는 코어위브(-11.9%), 모더나(약 -9%), 팔란티어(약 -7%), 메타(-3.7%), 넷플릭스(-2.9%), 테슬라(-2.1%)가 내렸습니다. 다음 주에는 테슬라·넷플릭스·메타 실적이 예정돼 있고, 연준은 10월 28일 회의를 엽니다. 시장은 10월 금리 인상 가능성을 약 15%로 보고 있습니다.
Sources: Google Finance · Yahoo Finance live coverage (Oct. 16, 2026). For information only; not investment advice.